ON THIS PAGE
Progress0%

Our Global Presence :




Blockchain in payments improves transaction efficiency by enabling shared-ledger verification, faster digital asset settlement, and reduced dependence on certain intermediaries in cross-border transactions.
Stablecoins, cryptocurrencies, and tokenized deposits serve different payment requirements, making asset selection, liquidity, redemption mechanisms, and regulatory compliance essential for enterprise adoption.
Blockchain payment solutions can reduce settlement delays, transaction costs, and manual reconciliation, particularly for businesses managing international supplier payments, remittances, and recurring payouts.
Real-world applications extend across multiple industries, including B2B payments, e-commerce, international payroll, merchant transactions, and smart contract-based payment automation.
Blockchain and traditional payment systems offer different operational advantages, with hybrid payment infrastructure often providing a practical approach to balancing settlement efficiency, banking access, compliance, and recipient convenience.
Regulatory compliance, liquidity, security, and system integration remain major adoption challenges, requiring businesses to address AML/KYC requirements, private key management, fiat conversion, and transaction irreversibility.
Successful blockchain payment implementation requires a phased approach, starting with payment workflow assessment, provider and network selection, financial system integration, security controls, and pilot testing against measurable business outcomes.
A payment can cross international borders in seconds, yet settlement may take days. For businesses managing overseas suppliers, employees, and customers, intermediary banks, currency conversions, and fragmented financial records can create delays, additional costs, and operational complexity.
The growing adoption of blockchain-based payments reflects efforts to address these challenges. According to research from Allium cited by Visa in October 2026, annual stablecoin payment volume was estimated between $401 billion and $527 billion, indicating increasing commercial activity through blockchain-enabled payment infrastructure.
Blockchain in payments offers an alternative approach by enabling transactions to be verified, recorded, and settled through shared digital networks. This can reduce certain intermediary dependencies, improve payment traceability, and support automated financial transactions. For businesses processing recurring international payments, these capabilities may help address settlement delays, reconciliation efforts, and unpredictable transaction costs.
Commercial adoption is also accelerating. In September 2026, Visa reported that its stablecoin settlement volume exceeded a $20 billion annualized run rate, representing more than 15-fold year-over-year growth. This development highlights how established financial institutions are integrating blockchain into existing payment operations rather than replacing traditional banking systems entirely.
For businesses evaluating blockchain payment solutions, the opportunity lies in identifying where the technology can deliver measurable improvements. This guide examines how blockchain payment processing works, its benefits, real-world applications, adoption challenges, and key implementation considerations.
Blockchain in payments refers to the use of blockchain networks to transfer, verify, record, and settle financial transactions. Built on distributed ledger technology (DLT), these networks maintain shared transaction records across participating systems, enabling payment verification and reducing dependence on separate reconciliation processes.
Unlike conventional international payments, which may involve multiple banks and intermediaries, blockchain-based transactions can transfer digital value through a shared network. For example, a US business paying an overseas supplier may use a blockchain payment provider to transfer digital assets, followed by currency conversion and local payout where required.
However, blockchain does not necessarily eliminate financial intermediaries. Banks and payment providers may still handle compliance, liquidity, custody, and conversion into conventional currencies.
Blockchain payment systems support different types of digital assets depending on business requirements, transaction value, and regulatory conditions.
Each asset carries different requirements concerning ownership, redemption, liquidity, and regulatory oversight. For blockchain-based payment systems for financial institutions, selecting an appropriate settlement asset is essential for maintaining transaction reliability and managing financial risks.
As highlighted by the Bank for International Settlements, trust, monetary integrity, and safeguards remain important as digital money develops. For businesses, the priority is ensuring that blockchain payments deliver usable funds securely, efficiently, and in accordance with applicable financial requirements.
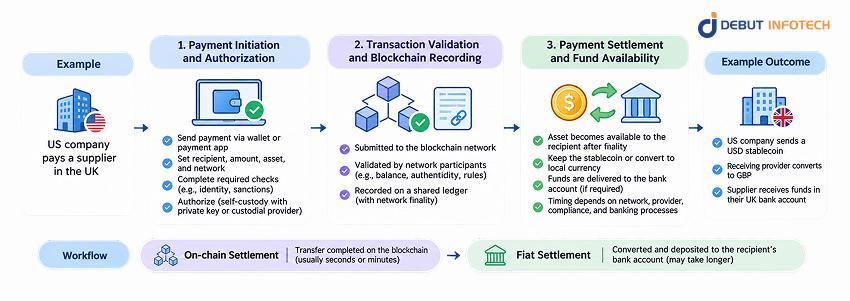
A blockchain payment follows a sequence of activities involving transaction initiation, authorization, network validation, and settlement. Although the underlying architecture differs from conventional banking infrastructure, the customer-facing experience can remain familiar. A user initiates a transaction through a wallet, payment application, or financial service provider, while the connected systems handle transaction verification and the movement of value.
Understanding how blockchain payment processing works requires distinguishing between the transfer recorded on a blockchain and the complete financial transaction. A digital asset may reach a recipient’s wallet quickly, but conversion into local currency and deposit into a conventional account may introduce additional processing steps.
The process begins when a sender instructs a supported application or payment provider to transfer a specified amount. The sender may interact directly with a blockchain wallet or use an existing payment interface that connects to blockchain services in the background.
Depending on the payment arrangement, the system establishes the recipient’s wallet address or payment account, transaction amount, selected digital asset, applicable network, and available balance. It may also initiate identity verification, sanctions screening, or other controls required by the service provider.
Authorization depends on how the payment service manages digital assets. In a self-custodied wallet, the sender typically approves the transfer using a private cryptographic key. Under a custodial arrangement, an authorized provider may manage transaction signing and submission according to its own access and security controls.
This distinction affects how businesses manage responsibility for transactions. A company handling its own private keys must establish secure storage, approval procedures, and recovery arrangements. A company using a managed payment provider needs to assess the provider’s custody model, authorization mechanisms, and operational responsibilities.
Once authorized, the transaction is submitted to the selected blockchain network. Validators or other designated participants verify whether it satisfies the network’s requirements, including transaction authenticity, available funds, and rules preventing conflicting transfers.
After validation, the transaction is recorded according to the network’s consensus and finality mechanisms. On public blockchains, details such as wallet addresses, transaction amounts, and timestamps may be visible through blockchain explorers. Permissioned networks can establish different visibility and access controls based on the roles of participating institutions.
The shared ledger provides a consistent reference for the on-chain transaction. This can reduce discrepancies between systems that would otherwise maintain separate records of the same transfer.
However, transaction validation has a specific purpose. A blockchain network can confirm that a transfer occurred under its rules, but it cannot independently establish whether the underlying invoice was accurate, whether goods were delivered, or whether the sender complied with every applicable legal obligation.
These checks remain the responsibility of connected business systems, authorized participants, and relevant financial institutions.
After a transaction reaches the required level of network finality, the transferred digital asset becomes available to the recipient under the applicable wallet or custody arrangement.
What happens next depends on how the payment is intended to be received.
A business accepting stablecoins may retain the assets for future payments or treasury activities. Another recipient may require funds in a conventional bank account, making currency conversion and local payout necessary before the payment is commercially complete.
This creates an important distinction between two stages:
A blockchain transaction may achieve network finality within seconds or minutes while the full payment takes longer. Processing times depend on the chosen network, transaction conditions, provider arrangements, compliance procedures, and payout destination.
For this reason, real-time payment settlement should not be assumed to mean immediate access to funds in every payment arrangement.
Consider a US company paying a supplier in another country, say the United Kingdom. Under a supported blockchain payment service, the company initiates a dollar-denominated payment through its provider. The provider transfers an eligible stablecoin over the selected blockchain network, and a receiving provider converts the asset into pounds before delivering the funds to the supplier’s bank account.
The on-chain portion may settle quickly, but the complete process still depends on foreign exchange availability, provider processing, compliance checks, and access to local banking infrastructure.
For the company, success is measured through the supplier’s receipt of the correct amount, the total cost of the transaction, settlement predictability, and the ability to reconcile the payment with the corresponding invoice.
This example illustrates an important characteristic of blockchain technology for cross-border payments: its value often comes from improving a specific stage of the payment process rather than replacing every institution involved in completing the transaction.
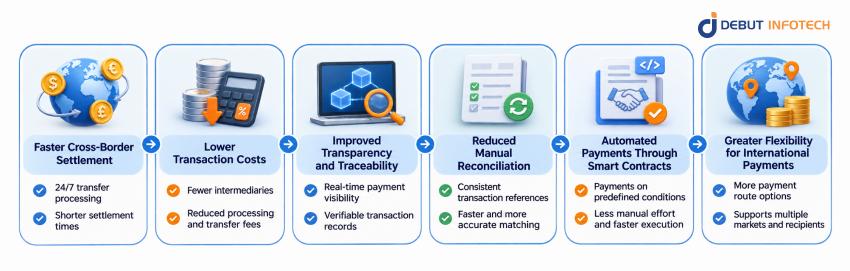
The benefits of blockchain technology in payment processing extend beyond faster transactions and lower fees. For businesses managing international payments, blockchain can improve settlement efficiency, transaction visibility, reconciliation, and payment automation. However, the actual value depends on network capabilities, payment providers, transaction volumes, and integration with existing financial systems.
International payments often pass through multiple financial institutions, with processing affected by banking hours, intermediary arrangements, and local clearing schedules. These dependencies can delay fund availability and complicate cash flow planning.
Blockchain-based payment networks can enable continuous transaction processing, allowing eligible digital assets to move between participants without following every stage of conventional correspondent banking. Visa’s USDC settlement initiative demonstrates how participating institutions can settle certain obligations using blockchain infrastructure, including outside regular banking hours.
For businesses, shorter settlement periods can improve liquidity management and payment predictability. However, actual completion times still depend on currency conversion, compliance checks, and local payout arrangements.
Traditional cross-border transfers may involve intermediary bank charges, processing fees, foreign exchange spreads, and receiving costs. These expenses become significant for companies handling frequent international supplier or contractor payments.
Blockchain payment systems can reduce certain intermediary dependencies and associated processing costs. Yet savings are not guaranteed, as transactions may still involve network fees, payment provider charges, custody expenses, and currency conversion costs.
Businesses should compare the total cost of payment execution, including:
The financial advantage is strongest when lower end-to-end transaction costs can be demonstrated against existing payment methods.
Tracking international payments can be difficult when transaction information is distributed across banks and payment processors. Businesses may know that funds have been transferred but lack immediate visibility into their settlement status.
Blockchain provides a verifiable transaction record containing information such as transaction status, amount, timestamp, and wallet addresses, depending on network permissions. When linked with invoices or accounting systems, these records can improve payment tracking and reduce uncertainty.
For example, an accounts payable system can associate a supplier invoice with a blockchain transaction reference and update its records once the transfer is confirmed. This supports more consistent financial reporting, although sensitive transaction information still requires appropriate privacy and access controls.
Finance teams frequently spend time matching transactions with invoices, investigating discrepancies, and updating records across different payment platforms. These tasks become more complex when businesses use multiple international banking services.
Distributed ledger technology can simplify reconciliation by providing consistent transaction references that integrate with accounting and treasury applications. Confirmed payments can trigger corresponding record updates, allowing employees to focus on exceptions rather than checking every transaction manually.
However, accurate reconciliation still depends on reliable invoice data, system integrations, and procedures for handling failed or incomplete payments. Technologies such as AI for cash application can complement blockchain transaction records by automating invoice matching and identifying payment discrepancies that require further review.
Many business payments depend on predefined conditions, such as delivery approvals, contractual milestones, or scheduled payouts. Manual verification and repeated payment instructions can increase administrative effort.
Smart contracts in payments can automate eligible transfers when authorized systems confirm that specified conditions have been satisfied. For example, a supplier payment could be released after an approved delivery milestone is recorded.
This supports smart contract-based payment automation for businesses, particularly those managing recurring or multi-party transactions. Reliable implementation still requires secure authorization, accurate external data, and controls for disputes or incorrect instructions.
Businesses operating across multiple markets often face differences in banking access, payment methods, and settlement availability. Some international corridors offer efficient transfers, while others involve higher costs or limited provider coverage.
Blockchain-based payment services can expand transfer options where compatible wallets, regulated providers, and currency conversion services are available. They can also support eligible peer-to-peer payments between participants.
For businesses, the advantage is greater flexibility in selecting payment routes that meet recipient needs. However, accessibility depends on local regulations, liquidity, and the recipient’s ability to convert digital assets into usable funds.
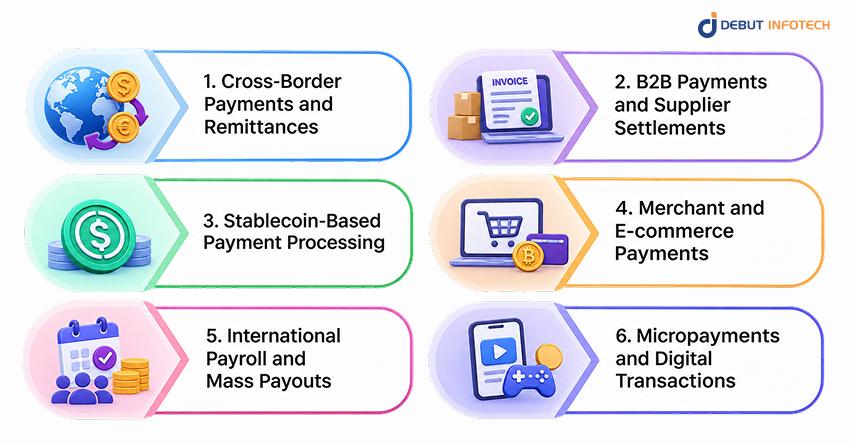
Blockchain payment solutions are gaining traction across industries where businesses manage international transactions, multiple currencies, and complex settlement processes. From cross-border remittances to automated payouts, these applications can reduce payment friction while improving transaction visibility and financial coordination.
The following use cases demonstrate how blockchain payment solutions for businesses can address specific operational challenges without requiring organizations to replace their existing financial infrastructure entirely.
Traditional cross-border payments often involve correspondent banks, intermediary charges, currency conversions, and different settlement schedules. These dependencies can increase processing costs and delay fund availability, particularly in payment corridors with limited banking infrastructure.
Blockchain for cross-border payments enables eligible digital assets to move between compatible financial institutions or payment providers through shared networks. This can reduce certain intermediary dependencies and support faster settlement, while local providers handle currency conversion and recipient payouts. Blockchain also supports P2P remittance models, where individuals can transfer digital assets directly or through supported platforms for international money transfers.
Real-world example: In September 2025, Swift announced plans for a blockchain-based shared ledger, collaborating with more than 30 financial institutions and Consensys. The initiative aims to support round-the-clock cross-border payments using regulated tokenized value.
For businesses, such developments indicate opportunities to improve international payment efficiency while maintaining connections with established financial institutions. Actual benefits still depend on compliance requirements, liquidity, and recipient access to funds.
Business-to-business payments involve more than transferring funds. Companies must match transactions with invoices, purchase orders, supplier agreements, and accounting records. Managing these requirements across countries and banking providers can create reconciliation delays and additional administrative work.
Blockchain-based payment systems can support B2B transactions through shared settlement records and integration with existing financial applications. For example, a manufacturer paying international suppliers could connect blockchain transaction references with approved invoices, allowing its accounting system to track confirmed transfers more consistently.
For enterprise blockchain solutions for payment processing, the value lies in simplifying payment coordination and improving visibility across the transaction lifecycle.
However, suppliers may still require local currency rather than digital assets. Businesses must therefore evaluate conversion costs, payout availability, and settlement reliability before adopting blockchain for supplier payments.
Stablecoins are digital assets designed to maintain a relatively stable value against a reference currency, typically the US dollar. Their intended price stability can make them more suitable for certain commercial payments than cryptocurrencies subject to substantial market fluctuations.
Businesses can use supported stablecoins for supplier payments, merchant transactions, and international settlements. Financial service providers may also incorporate stablecoin transfers into existing payment operations without requiring customers to manage digital assets directly.
Two examples illustrate this approach:
These applications demonstrate how digital asset payments can complement established financial services. Businesses must still evaluate issuer reliability, redemption rights, regulatory requirements, and liquidity before adopting stablecoin-based settlement.
The growing adoption of stablecoin payments also reflects a broader shift among fintech startups adopting blockchain to address payment inefficiencies and expand digital financial services. While payment processing is one application, these companies are also exploring blockchain across other financial operations.
Online merchants serving international customers may encounter high processing charges, currency conversion costs, and limited access to certain payment methods. Blockchain-enabled payments provide another acceptance option for customers using supported digital assets.
During checkout, customers can authorize transactions through compatible wallets or payment services. Merchants may receive the digital asset directly or use a provider that converts it into their preferred settlement currency.
For merchants accepting digital asset payments, gateway selection influences transaction monitoring, currency conversion, settlement arrangements, and customer experience. Understanding how a secure cryptocurrency payment gateway handles these requirements can help businesses assess suitable payment integrations before implementation.
This approach can support digital product businesses, online service providers, and international e-commerce platforms seeking greater payment flexibility.
However, merchants must address ordinary payment requirements, including refunds, incorrect amounts, duplicate transactions, and customer disputes. Since finalized blockchain transfers are generally irreversible at the network level, refund and recovery procedures require separate arrangements.
The priority is ensuring that blockchain payments remain convenient for customers and manageable for finance teams.
Businesses managing international contractors frequently encounter varying banking requirements, transaction costs, and settlement delays. These challenges increase when organizations process large volumes of recurring payments across multiple countries.
Blockchain-based payout services can transfer eligible digital assets through supported networks, allowing recipients to receive funds directly or convert them into local currency through payment providers.
For example, a company paying contractors across several markets could connect approved payout instructions with blockchain transactions and automatically associate transfer records with individual contractor accounts.
This can improve payout visibility and reduce reconciliation effort. However, employment regulations, tax obligations, and permitted payment methods vary by jurisdiction.
Businesses should therefore distinguish between contractor payouts and employee payroll, ensuring that their selected payment arrangements comply with applicable requirements.
Conventional payment processing can become expensive for small-value transactions because fixed fees may represent a significant portion of each payment. This creates challenges for businesses offering digital content, usage-based services, and low-cost transactions.
Blockchain-based payment networks may support micropayments where transaction fees and processing costs are sufficiently low.
Potential applications include:
For instance, a software provider could record customer API usage and periodically settle accumulated charges through a suitable blockchain payment network instead of processing numerous individual payments.
The commercial feasibility depends on transaction volume, network charges, customer authorization, and reconciliation requirements. Businesses should assess these factors before introducing blockchain-based micropayments into their digital payment infrastructure.
Blockchain-based payments and conventional payment systems differ in how they coordinate transfers, record transactions, and establish settlement. Yet comparing them as opposing technologies overlooks an important reality: traditional payment infrastructure already provides efficient services in many markets, while blockchain payment arrangements often depend on those same institutions for currency conversion, liquidity, and customer access.
Domestic instant payment systems can process eligible transfers rapidly. Card networks provide widespread acceptance and established dispute procedures. Banks offer regulated accounts, familiar financial controls, and access to national currencies.
Blockchain-based payment networks introduce different capabilities, particularly when digital assets need to move across participating systems without depending entirely on conventional settlement schedules.
The following comparison highlights their operational differences.
| Comparison factor | Traditional payment systems | Blockchain-based payment systems |
| Settlement speed | Ranges from near-instant domestic payments to multi-day international transfers | On-chain settlement can be rapid, although fiat conversion and payouts may take longer |
| Operating availability | Depends on institutions, payment networks, and settlement schedules | Many blockchain networks operate continuously, but providers may impose restrictions |
| Transaction costs | May include bank charges, processing fees, intermediary fees, and currency conversion spreads | May include network fees, provider charges, custody costs, and conversion expenses |
| Transaction visibility | Depends on payment providers, banking systems, and tracking services | Shared on-chain records may improve visibility into eligible transfers |
| Intermediaries | Commonly involves banks, payment processors, and clearing institutions | May reduce certain intermediary dependencies but often retains regulated service providers |
| Payment reversibility | Some methods support recalls, disputes, refunds, or chargebacks | Finalized transfers generally require a separate refund or recovery process |
| Currency support | Established access to conventional currencies | Depends on supported digital assets, providers, and local conversion services |
| Integration | Often uses mature banking APIs and payment gateways | Requires compatible blockchain, wallet, asset, and provider integrations |
| Compliance | Established obligations vary by jurisdiction and payment service | Financial crime, licensing, consumer protection, and reporting requirements still apply |
The comparison becomes useful when organizations relate these differences to their actual payment requirements.
A company making frequent international supplier payments may value extended settlement availability and consistent transaction tracking. A digital marketplace might benefit from programmable payment distribution. A financial institution could use blockchain settlement to support selected international payment arrangements.
The business case is less obvious where existing payment infrastructure already provides low-cost, reliable service. A retailer with efficient domestic card acceptance, for example, may gain little from introducing a new wallet-based payment method that requires additional support and reconciliation procedures.
Before adopting blockchain, businesses should establish the operational difference they expect it to deliver:
These factors provide a more useful decision framework than headline transaction speeds or network fee comparisons.
Adoption also does not need to involve replacing all existing payment methods. A company might retain conventional domestic payments while introducing blockchain settlement for selected international corridors. In many cases, a hybrid arrangement offers a more practical balance between new payment capabilities and established financial operations.
While blockchain can improve payment efficiency, businesses must address regulatory, security, and operational challenges before adoption. These concerns become more complex when transactions involve multiple jurisdictions, financial institutions, and digital assets. Understanding the major blockchain payment system implementation challenges helps organizations assess risks and develop reliable payment arrangements.
Blockchain payment regulations vary by jurisdiction, transaction type, and the digital assets involved. Businesses accepting stablecoins through payment providers may face different obligations than institutions offering custody, asset issuance, or payment transfer services.
Regulatory compliance in blockchain may involve anti-money laundering (AML), know-your-customer (KYC), sanctions screening, transaction monitoring, and licensing requirements.
Regulatory frameworks are evolving across major markets:
Businesses operating internationally must evaluate jurisdiction-specific requirements before selecting settlement assets or payment providers.
Blockchain transactions can settle quickly without guaranteeing immediate access to conventional currency. Recipients may need to convert digital assets into local funds, depending on payment preferences and operational requirements.
Conversion efficiency depends on market liquidity, exchange rates, payment provider capabilities, and local banking availability. Less-supported payment corridors may involve wider conversion spreads, withdrawal restrictions, or additional processing delays.
Stablecoin payments introduce further considerations regarding issuer reserves, redemption mechanisms, and liquidity availability. Businesses should assess whether the selected settlement asset can reliably maintain its intended value and support timely conversion.
The key consideration is not simply blockchain settlement speed but whether recipients obtain usable funds at a predictable cost.
Although blockchain networks use cryptographic security mechanisms, payment applications remain vulnerable to compromised credentials, incorrect wallet addresses, unauthorized access, and smart contract vulnerabilities.
Unlike certain conventional payment methods, finalized blockchain transactions generally cannot be reversed through the network. Businesses must therefore establish controls that reduce transaction errors and unauthorized transfers.
Important security measures include:
Organizations using smart contracts must also assess contract logic, access permissions, and external data dependencies. Payment security should cover the entire transaction process, from authorization to final settlement.
Blockchain networks differ in transaction capacity, confirmation times, settlement finality, and fee structures. Network congestion can increase transaction charges or delay confirmations, particularly during periods of high activity.
Businesses processing large payment volumes must evaluate whether the selected network can support consistent performance under realistic operating conditions. Failed transactions, temporary outages, and delayed confirmations also require appropriate exception-handling procedures.
Scaling technologies may improve throughput and reduce network fees, but they do not eliminate delays associated with compliance screening, currency conversion, or local payouts.
Blockchain payment solutions must connect with established banking services, payment gateways, accounting platforms, and enterprise applications to deliver operational improvements.
Integration challenges commonly involve transaction tracking, payment status updates, reconciliation, reporting, and exception management. Inconsistent data between blockchain networks and internal financial systems can create additional administrative work. For example, a business may achieve faster stablecoin settlement but still require manual reconciliation if transaction records are not connected to its accounting platform.
Organizations should also define responsibilities for failed conversions, delayed payouts, and transactions that settle on-chain but remain incomplete within conventional banking systems.
Successful integration depends on coordinating blockchain settlement with existing financial workflows, ensuring that improvements in transaction processing translate into measurable operational benefits.
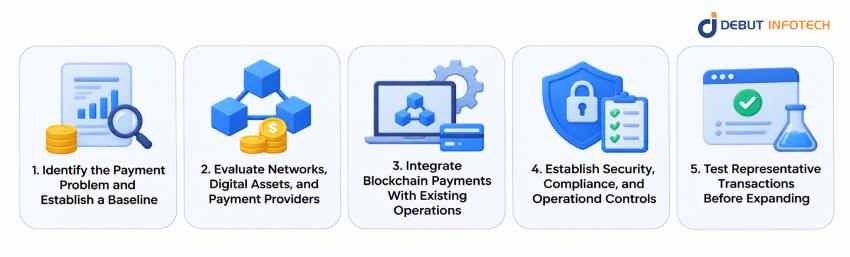
Introducing blockchain into business payment operations should begin with a defined operational requirement rather than a predetermined technology choice. The strongest implementation opportunities arise when organizations can identify recurring payment delays, avoidable costs, limited transaction visibility, or administrative processes that existing solutions do not adequately address.
A phased approach allows businesses to evaluate whether blockchain offers a measurable improvement before committing to broader integration or changes in financial operations.
The first step is to examine how payments currently move through the organization. Businesses should document the transaction types involved, participating institutions, processing timelines, costs, approval workflows, and common exceptions.
The objective is to determine where meaningful friction occurs.
For example, an organization may discover that its main challenge is not international settlement speed but the time finance employees spend matching supplier payments with invoices. Another may find that delays are concentrated in a small number of international payment corridors.
These differences influence whether blockchain is appropriate and which part of the payment process should change.
Establishing a baseline also makes future evaluation more reliable. Organizations can compare proposed payment arrangements against current completion times, transaction costs, reconciliation effort, and failure rates rather than making assumptions about potential improvements.
Once the business requirement is clear, organizations can assess the available settlement models.
The assessment should consider the selected blockchain network, supported digital assets, payment provider arrangements, geographic availability, transaction capacity, and applicable regulatory requirements.
Businesses should also examine how settlement assets are held, transferred, and converted. A provider offering inexpensive blockchain transfers may be unsuitable if it cannot support the recipient’s preferred currency or deliver funds reliably in the required jurisdiction.
Choosing between direct wallet transfers, managed stablecoin payment services, and hybrid banking arrangements depends on the intended users and operational responsibilities.
For many enterprises, working through an established payment provider can reduce the complexity of managing digital assets directly. Other organizations may have specific requirements that justify greater control over transaction authorization, custody, or settlement processes.
The preferred approach should follow the business model, not the perceived popularity of a blockchain network.
Payment functionality should connect with the applications and financial procedures employees already use.
For organizations considering custom blockchain payment solution development, the emphasis should be on maintaining consistent transaction information across payment services, accounting platforms, enterprise systems, and customer-facing applications.
Depending on the arrangement, integration may involve wallets, payment gateways, banking APIs, transaction monitoring services, treasury tools, or ERP systems.
The main requirement is that blockchain events translate into meaningful business records. A confirmed on-chain transfer should update the appropriate payment status, while any pending currency conversion or local payout should remain visible until the full transaction is completed.
Businesses should evaluate how different crypto payment gateways support existing financial applications, payment APIs, settlement reporting, and currency conversion. These considerations help determine whether a provider can accommodate current operations without creating additional reconciliation or administrative work.
The appropriate functionality depends on the payment model and the participants it serves. A merchant payment application has different requirements from a financial institution’s settlement service or an internal supplier payment platform.
Common capabilities may include secure payment authorization, transaction initiation, wallet connectivity, status tracking, transaction limits, reconciliation records, and integration with existing financial systems.
Services handling customer funds may also require identity verification, transaction screening, custody controls, and regulatory reporting. Other arrangements may need currency conversion, automated payouts, or configurable payment approval rules.
The goal is to identify the smallest set of capabilities that reliably supports the intended workflow rather than treating every available blockchain feature as a business requirement.
Before introducing live transactions, organizations must define how payments will be approved, monitored, recorded, and recovered when problems occur.
These controls should reflect the company’s role in the payment process, the settlement assets involved, and the applicable legal requirements.
A business accepting digital asset payments through a third-party provider faces different obligations from a company operating a financial service that holds or transfers customer assets.
Organizations should clarify responsibility for transaction authorization, custody, compliance screening, payment disputes, and operational incidents. They should also assess provider dependencies and establish procedures for service outages or delayed settlement.
These decisions influence whether the payment arrangement can remain reliable as transaction activity increases.
A controlled pilot provides an opportunity to examine the proposed payment process under realistic conditions without immediately exposing the business to enterprise-wide operational changes.
Testing should include successful transactions, incorrect recipient information, insufficient balances, delayed confirmations, failed conversions, duplicate instructions, and reconciliation exceptions.
Organizations should compare pilot outcomes against their existing payment arrangements using defined performance indicators.
Relevant measures include:
A pilot that demonstrates technical transaction success but does not improve operational performance may not justify broader deployment.
Expansion should depend on measurable results, reliable integrations, appropriate compliance controls, and evidence that the payment service works for both senders and recipients.
The objective is not to replace functioning infrastructure unnecessarily. It is to introduce a better payment arrangement where the evidence supports doing so.
Blockchain is creating additional options for how businesses and financial institutions move, record, and settle payments. Cross-border transfers, stablecoin settlement, supplier payments, and automated payouts are among the applications where it can address limitations associated with conventional payment arrangements.
Commercial developments involving Visa, Stripe, and Swift indicate growing interest in combining blockchain functionality with established financial services. Yet adoption remains dependent on practical considerations, including liquidity, regulatory obligations, recipient access, integration complexity, and the total cost of completing a transaction.
For businesses, the starting point should be the payment problem rather than the technology. A blockchain arrangement that improves settlement speed but introduces conversion delays or additional reconciliation work may offer little advantage. A solution that reduces recurring payment friction while maintaining reliable financial controls presents a stronger case.
At Debut Infotech, we help organizations assess these trade-offs and identify where blockchain can improve existing payment operations. Through our Blockchain Development Services, we support businesses evaluating blockchain settlement models, payment automation, and integration requirements according to their operational objectives.
Our Fintech Software Development Services help organizations connect payment capabilities with existing financial systems, while our Crypto Wallet Development expertise supports wallet-based transaction requirements where appropriate.
Considering blockchain for your payment operations? Connect with Debut Infotech to evaluate suitable payment workflows, understand the implementation requirements, and determine where blockchain can deliver measurable business value.
Blockchain payment systems use a shared digital ledger to validate and record eligible transactions. A sender initiates and authorizes a payment, the network processes the transfer according to its rules, and the recipient receives the digital asset after the required confirmation or finality conditions are met.
When the recipient requires conventional currency, additional conversion and banking processes may be necessary. The complete payment time therefore depends on both the blockchain network and the connected financial services.
Blockchain can support faster settlement, improved transaction tracking, reduced reconciliation effort, and lower costs in suitable payment arrangements. Smart contracts can also automate predefined payment instructions, while compatible digital asset networks may provide greater flexibility for certain international transfers.
These benefits depend on the network, payment providers, liquidity, regulatory requirements, and integration with existing business systems.
Businesses can use blockchain for eligible supplier payments, cross-border transfers, stablecoin acceptance, contractor payouts, and automated payment distribution. They may access these capabilities through established payment providers or integrate blockchain functionality into their own financial applications.
The suitable approach depends on transaction volume, payment destinations, recipient requirements, and operational responsibilities.
The main challenges include regulatory compliance, fiat conversion, liquidity, transaction security, payment irreversibility, network performance, and integration with conventional financial software.
Businesses must also establish procedures for refunds, failed transfers, duplicate transactions, and service interruptions. These requirements should be evaluated before introducing blockchain into live payment operations.
Blockchain payments can be faster or less expensive in certain international payment corridors, but the advantage is not universal. A rapid on-chain transfer may still require conversion and local banking processes before the recipient receives usable funds.
Businesses should compare the complete transaction cost and settlement time against available conventional payment methods rather than relying only on blockchain confirmation speeds or network fees.
Businesses should assess their existing payment challenges, transaction volumes, recipient locations, settlement assets, regulatory requirements, provider capabilities, and integration needs.
Security controls, liquidity availability, reconciliation processes, and exception handling are equally important. A limited pilot with measurable performance targets can help establish whether blockchain provides sufficient operational value to justify broader adoption.
Our Latest Insights
USA
2501 Chatham, Rd Suite R Springfield, IL 62704
+1-708-515-4004
info@debutinfotech.com
UK
7 Pound Close, Yarnton, Oxfordshire, OX51QG
+44-770-304-0079
info@debutinfotech.com
Canada
154 Eden Oak Trail, Kitchener, ON N2A 0H9
+1-708-515-4004
info@debutinfotech.com
INDIA
Sector 101-A, Plot No: I-42, IT City Rd, JLPL Industrial Area, Mohali, PB 140306
9888402396
info@debutinfotech.com